Skip to content
SIAT PAPER 2026Open the research page
Cryptoverso

MOIRA: where traders are positioned on options

Positioning read from the options flow. A measurement, never an instruction.

Shows who is positioned
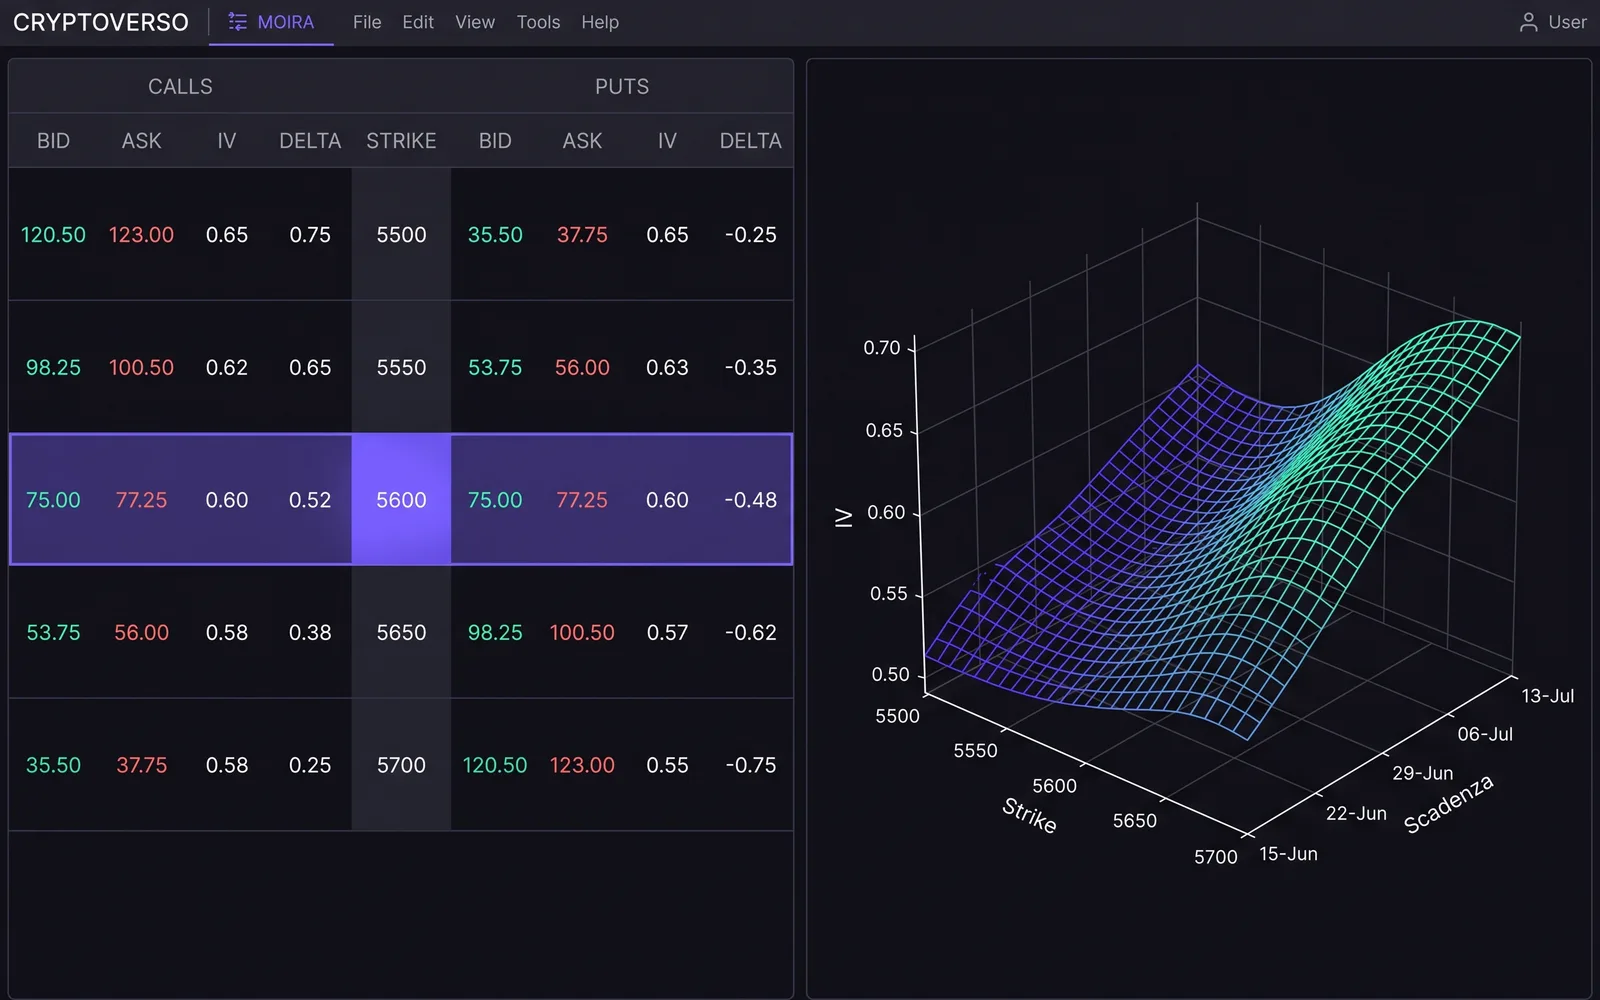
Reconstructed interface of MOIRA: option chain by expiry and strike, with implied volatility and Greeks.
MOIRA: the option chain and its Greeks.

What it measures

Open interest

By expiry and by strike.

Market maker exposure

Where they are exposed, by strike.

Put/call ratio

The weight of puts against calls.

Block flow

The large-size trades.

Theoretical price

The gap from the market, with confidence.

Calibrated surface

Volatility by strike and expiry.

Implied volatility surface of MOIRA, as a grid in perspective: strikes run to the right, from the lowest to the highest; expiries run to the left, from the nearest to the furthest; implied volatility is the height. Each expiry profile shows the smile: volatility rises as you move away from the forward price, and it rises more below than above. Distant expiries sit higher and are flatter. The at-the-money profile is highlighted.

Illustrative values from a declared parametrisation, not a real chain: the shape of the data, not a price.

Research already done

Years of testing, inside an add-on

  • Put to the test: which pricing models hold when the volatility surface deforms.
  • Only what holds up goes live.
  • The copilot builds tools; research takes years.

What it costs

Options add-on, yearly

coming soon

390 €/year + VAT

  • Plus the Workstation base: 339 €/year + VAT
  • Also included in: Ecosystem · Ecosystem Algo

Does today

  • Greeks validated against reference libraries.

Does not do

  • No footprint on the chain.
  • Today it is a command-line engine.

The scope

  • It runs on your own data.
  • The outcomes stay yours.
  • Automatic orders: planned, after the legal opinion.

Where the method is taught

The booksThe publications